Master the Envelope Budgeting Method in Easy Steps
Take control of spending with the classic envelope method. Follow simple, step-by-step guidance to set limits, stay on track, and grow savings fast.
Step 1: Grasp the Core Idea
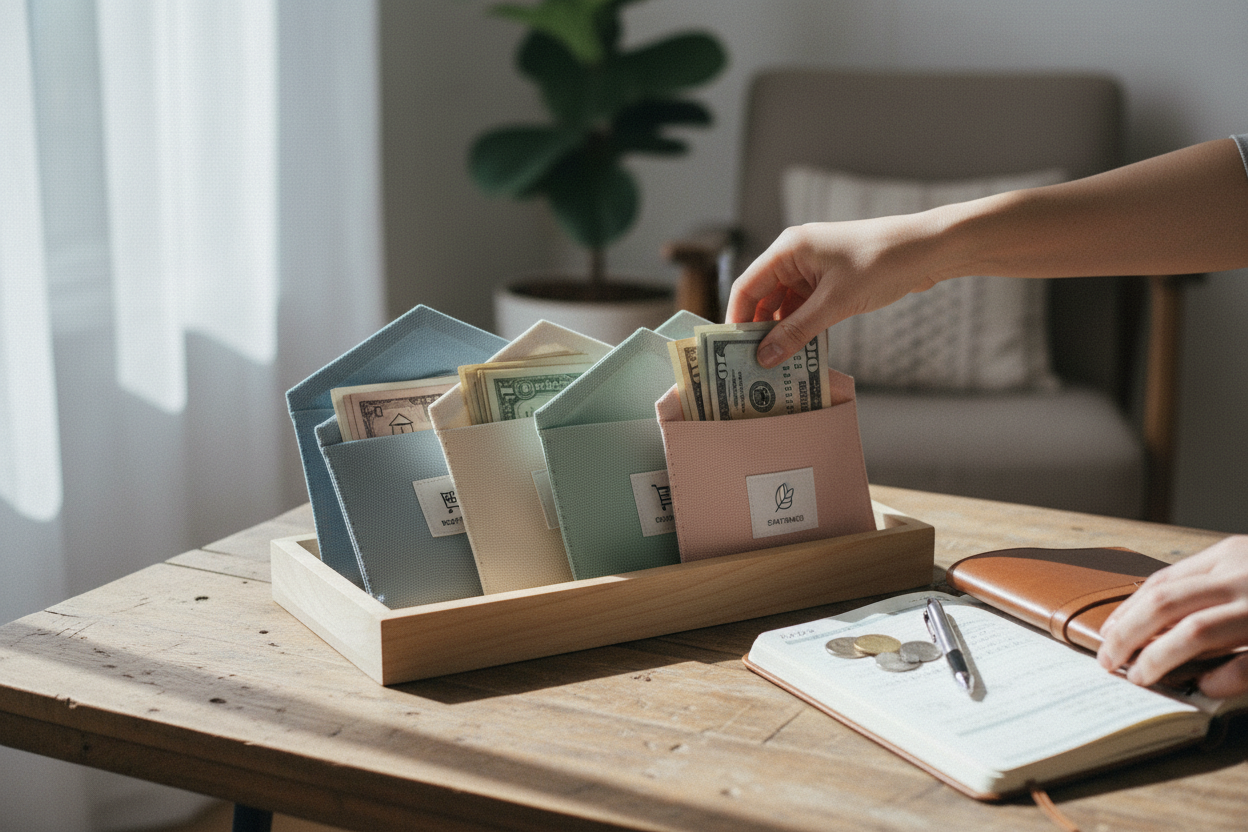
The Envelope Budgeting method is a simple, behavior-friendly way to control spending and grow confidence with money. You set spending limits by assigning cash or digital balances to labeled envelopes, like Groceries or Transportation, and then spend only from the matching envelope. Each dollar has a job, turning vague intentions into clear boundaries. Because envelopes make limits visible, they help prevent impulse buys and reduce decision fatigue. The method also brings zero-based clarity, encouraging you to allocate income with purpose rather than guessing as you go. You can use physical cash for tactile accountability or digital categories for convenience, and both honor the same rules. This approach is ideal for beginners who want structure and for seasoned budgeters who want tighter cash flow control. By separating money into focused buckets, you create a practical feedback loop: if one envelope runs low, you pause or re-prioritize, rather than sliding into debt. The result is momentum, less stress, and consistent, value-driven choices.
Step 2: Choose Smart Categories
Start with must-have categories, then add flexible ones. Common essentials include Rent or Mortgage, Utilities, Groceries, Transportation, Insurance, and Minimum Debt Payments. Add variable expenses such as Dining Out, Personal Care, Entertainment, and Household. Finally, include sinking funds for non-monthly costs, like Car Maintenance, Gifts, Travel, Medical, and Annual Subscriptions. Keep the list lean enough to manage daily but detailed enough to reflect real life. Many people do well with a balanced set that includes needs, wants, savings, and debt. Give each envelope a clear purpose to reduce overlap, and avoid creating too many ultra-specific categories that invite confusion. When in doubt, combine similar expenses. If you split groceries and household supplies, for example, be consistent with what belongs where. The goal is to make decisions easy at the store, not harder. Strong categories turn your budget into a decision system, so that you simply follow pre-made choices rather than negotiating with yourself in the moment.
Step 3: Allocate Your Income With Intention
List your total take-home income, then fund essentials first, followed by savings and debt goals, and finally discretionary spending. A simple framework is Needs, Wants, and Goals. Prioritize pay-yourself-first contributions to savings, sinking funds, and extra debt payments, even if the amounts start small. If your income varies, build a base budget that covers core envelopes and then add percentages for extras when paychecks arrive. Consider creating a buffer envelope to absorb life's little surprises, which reduces the temptation to raid other categories. When you assign amounts, round to practical numbers so cash stuffing is quick and digital transfers are tidy. If you are transitioning from cards, set conservative limits at first to learn your true patterns. Stay realistic and honest with actual costs, not idealized versions. Over time, calibrate the amounts until your envelopes match your values and cash flow rhythms, ensuring every dollar is working for a purpose you care about.
Step 4: Build and Label Your Envelopes
Choose physical envelopes, a cash wallet, or a digital tool with clearly labeled categories. Write short, obvious names that match your shopping habits to avoid mix-ups at the register. Keep a simple reference card listing envelope amounts and refill dates. If using cash, store it safely at home and carry only what you need for the day or week. Consider color-coding or grouping envelopes by type, such as essentials, flexible spending, and sinking funds. For online purchases, create a holding envelope so you can set aside cash or note a transfer immediately, preventing accidental double-spending. Include a small Miscellaneous envelope to catch odd expenses that do not fit elsewhere. The act of labeling turns vague intentions into visible commitments, making it easier to pause before spending. Remember, the magic lies in friction that is helpful, not painful. Keep tools simple, accessible, and consistent so the system supports you even on busy days.
Step 5: Spend and Track in Real Time
Follow one core rule: spend from the matching envelope only. Before you buy, check your balance. If the envelope is short, you can wait, adjust your plan, or intentionally move money from another category. This turns every purchase into a conscious choice. Record transactions immediately using a tiny ledger inside the envelope, a notes app, or a budgeting tool. A daily sixty-second balance check keeps everything accurate and prevents pileups. For online orders, move cash to your holding envelope or log the transfer so totals stay clean. When eating out or running errands, keep receipts until you log them, then toss or file them weekly. Guard against slippery borrowing between envelopes. Small, frequent tracking beats occasional heavy catch-up. By keeping your numbers current, you transform envelopes from guesses into real-time dashboards that reflect your values. This clarity builds confidence and frees mental space, because you know what is available at a glance.
Step 6: Refill, Review, and Adjust With Purpose
On your refill day, fund envelopes in a consistent sequence: essentials, savings and debt, sinking funds, then flexible spending. Reconcile balances, roll over any leftovers, and decide whether to sweep surpluses into savings or next month's priorities. If you overspent, look for the pattern, not the guilt. Tighten caps where spending is consistently high, or acknowledge that some costs were underestimated and recalibrate. Make seasonal tweaks to categories like Utilities, Travel, and Gifts. If one envelope is always empty early, split it into two clearer purposes, or add a small buffer for surprise needs. Track a few simple metrics such as total savings rate, debt reduction momentum, and cash on hand. Celebrate small wins so motivation stays high. Most importantly, use your review to protect priorities before funding conveniences. Repeating this loop turns envelope budgeting into a steady habit, where each cycle teaches you how to aim your money more accurately.
Step 7: Level Up and Stay Consistent
Once the basics feel smooth, refine your system. For irregular income, use a percentage-based plan that funds essentials first, sets aside taxes if relevant, builds sinking funds, and then allocates to wants. Automate transfers for savings and debt so progress happens even on busy weeks. Expand sinking funds to cover car repairs, healthcare, home updates, and future fun, turning surprises into planned events. When debt shrinks, redirect freed-up envelopes into a debt snowball or savings milestones. Build resilience with a dedicated emergency fund, and refill it promptly after any use. Keep motivation alive with visual trackers and short check-ins with a partner or accountability buddy. If you fall off, reset quickly by funding only essentials for a cycle or two. Avoid perfectionism; aim for consistency over brilliance. The real win is alignment: envelopes that reflect your values, protect your time, and make everyday spending calm, intentional, and sustainable.